A budget is your supplement brand’s plan for the year: what you expect to sell, spend, and earn. A forecast updates that plan every month as real sales, ingredient costs, and launch dates come in. Keep both, side by side, so you always know how far you’ve drifted from plan.
SAL Accounting helps supplement brands build both. By the end, you’ll have a monthly model you can actually update.
Once you have a forecast, see what it means for operating profit with the Ecommerce EBITDA Calculator.
Quick Takeaways
- A budget is your fixed plan for the year. A forecast is your latest estimate, updated every month.
- Build revenue from drivers like subscribers, orders, and price, not a flat percentage on last year.
- Plan COGS from real ingredient, packaging, and production costs, not a fixed share of sales.
- Compare budget with actual results every month, and find the cause of each big gap.
- Replace finished months with actual results, and update only the assumptions that changed.
- Test big decisions with base, downside, and upside scenarios.
Supplement forecasts break when production runs, subscriptions, and ingredient costs aren’t recorded right. Our ecommerce bookkeeping services keep those numbers clean every month, so your budget starts from figures you can trust.
What Is the Difference Between a Budget and a Financial Forecast for a Supplement Brand?
A budget is your original plan for the year, while a forecast is your latest estimate of what will actually happen.
Don’t rewrite the budget every time results change. Keep the approved budget and the updated forecast side by side, so you can see whether you’re ahead of plan or behind it.
| Item | Budget | Financial Forecast |
|---|---|---|
| Purpose | Sets the original plan | Shows the latest likely result |
| Starting point | Goals and assumptions | Actual results plus updated assumptions |
| Updates | Kept as approved | Updated as things change |
| Main use | A target to measure against | Decisions on marketing, hiring, and production |
Both focus on profit: revenue, gross profit, expenses, and operating profit. A cash flow forecast is a separate tool that shows when money actually moves in and out of your bank. Why the two don’t match is set out in ecommerce profit vs cash flow, and the timing side is built in a supplement cash flow forecast. Once your forecast changes, check that plan too.
What Numbers Does a Supplement Ecommerce Business Need Before It Builds a Budget?
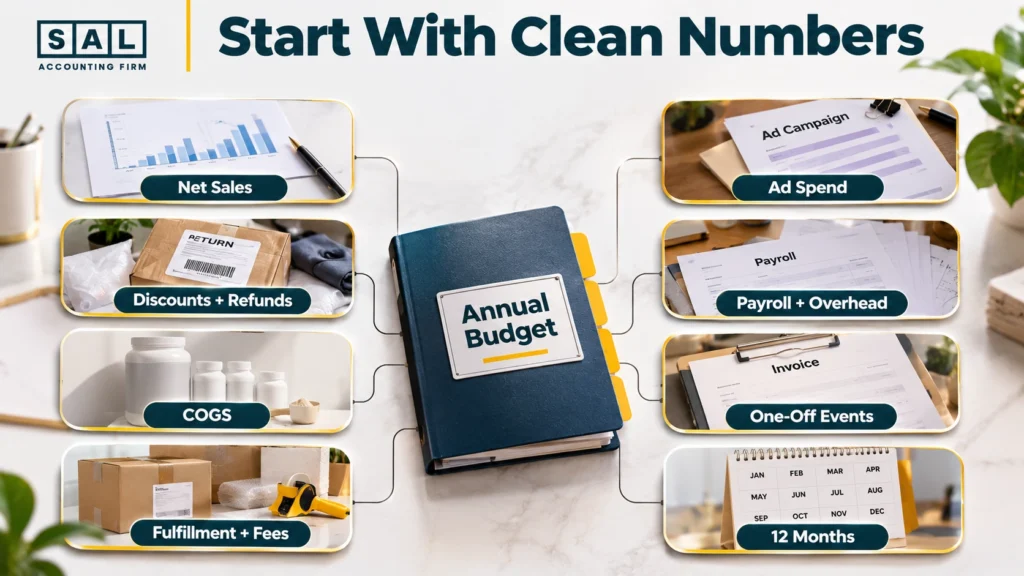
Start with 12 months of reliable monthly results from your books, broken down by channel and product. Pull together:
- Net sales, discounts, refunds, and returns
- COGS for the units you sold
- Fulfillment, payment processing, and marketplace fees
- Ad spend by channel
- Payroll, contractors, software, rent, and other overhead
- One-off events, like product launches or big production runs, that make some months unusual
Use recognized sales, not marketplace deposits. A deposit has already had fees, refunds, and reserves taken out, so it understates your revenue. The steps to separate the two are in revenue vs payout reconciliation for supplement stores.
If your books have gaps, fix them first. A budget built on messy numbers will mislead you all year. An ecommerce bookkeeping checklist shows what clean monthly books should include.
How Do You Forecast Revenue for a Supplement Ecommerce Business?
Build revenue from the drivers that create sales, like subscribers, one-time orders, and price, by channel and month.
Don’t just add 15% to last year. For a supplement brand, revenue usually comes from two streams:
- Subscription revenue = Active subscribers × Average order value × Orders per month
- One-time revenue = Orders × Average order value
Forecast each sales channel separately, because fees and growth often differ between your own store and Amazon.
| Revenue Driver | What to Estimate | What Can Change It |
|---|---|---|
| Active subscribers | New subscribers minus cancellations | Retention, promotions, product quality |
| One-time orders | Orders by month and channel | Ads, launches, inventory availability |
| Average order value | Net price after discounts | Bundles, discounts, product mix |
| Returns and refunds | Expected reduction to sales | Product issues, promotions |
| Channel mix | Share of sales by channel | Marketplace growth, site conversion |
How many subscribers stay, and how long, drives a big share of the forecast. That’s why it’s worth knowing your online supplement subscription profitability before you budget. Forecasting by channel is easier when you already track a channel-level P&L.
How Should a Supplement Brand Forecast COGS and Gross Margin?
Forecast COGS from your real unit costs for each product, not as a fixed share of sales.
Revenue − COGS = Gross profit
Supplement unit costs move for reasons that have nothing to do with sales volume. A new ingredient price, a packaging change, or a different product mix can shift your margin even if sales stay flat. Update your unit costs whenever a supplier quote or production run changes them. Ingredient and packaging changes can move margin more than most founders expect, and the size of that effect is worked through in ingredient and packaging costs for supplement ecommerce.
Remember that inventory isn’t an expense when you buy it. Under IAS 2, inventory costs become an expense when the products are sold. A big production run in March shows up in COGS over the months those units sell. IAS 2 applies under IFRS, and many Canadian private companies use ASPE instead, so confirm your framework with your accountant.
How Do Production Runs and Inventory Affect a Supplement Brand’s Forecast?
Production timing decides when you can sell, so a late run can push sales out by weeks or months. Build these into your forecast:
- Production dates, and how long they take to reach your warehouse
- Co-packer minimums that set how much you have to order
- Launch dates for new products
- An allowance for inventory that may expire before it sells
A delayed run moves sales into later months. Minimums can leave you holding more inventory than you’ll sell soon, which raises the risk of expired units. Keeping each run’s numbers straight starts with reconciling every co-packer production run, and planning for units that might not sell in time is part of accounting for expired supplement inventory.
Which Selling and Operating Expenses Should a Supplement Brand Budget For?
Budget for the costs of serving each sale separately from the overhead you pay no matter what you sell. Selling costs move with orders:
- Fulfillment and shipping
- Payment processing and marketplace fees
- Ads, affiliates, and promotions
Overhead changes when you decide to change it:
- Payroll, and the month each new hire starts
- Contractors, software, rent, insurance, and professional fees
- Expected one-time costs, budgeted in the month they’ll happen
Tie each cost to what drives it. Fulfillment rises with orders, while payroll jumps when someone new starts. Whether each new customer is worth what you spend to win them is the question online supplement unit economics answers, and it should shape your ad budget.
How Do You Build a Monthly Operating Budget for a Supplement Brand?
Build each month separately, using the same lines your monthly reports already use.
| Monthly Line | What It Includes | Main Driver |
|---|---|---|
| Revenue | Net recognized sales | Subscribers, orders, average order value |
| COGS | Product cost of units sold | Volume, product mix, unit cost |
| Gross profit | Revenue minus COGS | Revenue and margin |
| Selling costs | Fulfillment, processing, channel fees | Orders and channel mix |
| Marketing | Ads, affiliates, promotions | Spend plan and campaign timing |
| Payroll and overhead | Staff, contractors, software, rent | Headcount and operating plan |
| Operating profit | Gross profit minus all expenses | Everything above |
Don’t divide the annual target by 12. Launches, promotions, and inventory availability make some months much bigger than others.
Pro Tip: Use the same line names in your budget as in your monthly financial statements. Comparing them each month then takes minutes, not hours.
How Do You Compare Budget With Actual Results for a Supplement Brand?
Compare each closed month with the budget, line by line, and find the cause of every large gap. Here’s an illustrative April, with variance shown as actual minus budget:
| Line | Budget | Actual | Variance | What to Check |
|---|---|---|---|---|
| Revenue | $200,000 | $185,000 | −$15,000 | Fewer subscribers, lower price, or a delayed launch? |
| COGS | $70,000 | $75,000 | +$5,000 | Higher unit costs, or a different product mix? |
| Marketing | $25,000 | $31,000 | +$6,000 | Extra spend, or a campaign that started early? |
| Payroll | $30,000 | $35,000 | +$5,000 | An earlier hire, or extra contractor hours? |
Pick one way to show variance and stick with it. A gap isn’t automatically bad news. If marketing ran $6,000 over because a campaign started early, the real question is whether it brought in enough extra profit to pay for itself.
Which reports to review alongside this comparison is covered in financial reports for supplement businesses.
How Do You Turn a Supplement Budget Into a Rolling Forecast?
Replace each finished month with actual results, then update the months still ahead.
January–March actuals + April–December updated forecast = Latest full-year forecast
The original budget stays untouched. If the first quarter shows fewer subscribers and higher production costs, use those facts to revise the rest of the year, but only change an assumption when new information supports it. Updating the forecast is much easier when you close the books on time every month, which is why it belongs right after your month-end close for supplement brands.
Case Study: How Melissa’s Supplement Brand in The Junction, Toronto Rebuilds Her Forecast1
Melissa sells collagen and greens powders online from a small office in The Junction, Toronto. Her budget assumed steady growth and a new product launch in April.
The problem: By May, her subscriber count is below plan, her launch has slipped to July, and her ingredient costs have gone up. Her budget was built on one growth number, so she can’t tell whether her year-end profit target still holds.
What we do: We rebuild her forecast from drivers: subscribers, cancellations, average order value, and unit costs by product. We swap in her actual results for January to April, move the launch to July, and keep her original budget beside it for comparison.
The result: Melissa sees her full-year profit is tracking about $95,000 below budget, and exactly why. She trims ad spend on her weakest product and holds off on one planned hire until the launch proves out.
Which Forecast Assumptions Matter Most for a Supplement Brand?
Focus on the few assumptions that move your profit the most, and review them every month. For most supplement brands, these are:
- Subscriber growth and cancellations
- Average order value and discounts
- Ingredient, packaging, and manufacturing costs
- Ad spend and how well it converts
- Launch dates and inventory availability
- Hiring dates and payroll
For ingredient costs, your own supplier quotes come first. For a wider signal, Statistics Canada’s Raw Materials Price Index tracks what Canadian manufacturers pay for key raw materials. If you buy in US dollars, use one consistent exchange rate in your forecast, such as the Bank of Canada’s daily rate, so currency swings don’t look like cost changes.
Whenever you change an assumption, note what changed, why, and which months it affects.
How Can Scenarios Help a Supplement Brand Make Big Decisions?
Build three simple versions of your forecast, so you can see what happens if things go better or worse.
| Scenario | Assumptions | Possible Decision |
|---|---|---|
| Base case | Most likely demand, costs, and timing | Stick with the current plan |
| Downside case | Fewer subscribers, a higher ingredient cost, or a late launch | Delay a hire or cut extra spending |
| Upside case | Faster growth or better margins | Plan bigger production runs |
Use scenarios for decisions that matter, like a new product launch, a bigger production run, or a jump in ad spend. Bigger plans also tie up more cash in inventory, which is why it helps to know your working capital for a supplement business before you commit.
Case Study: How Kyle’s Supplement Brand in Churchill Meadows, Mississauga Tests a Bigger Production Run2
Kyle sells sleep and electrolyte supplements online from a warehouse unit in Churchill Meadows, Mississauga. His co-packer offers a lower unit price if he doubles his next production run.
The problem: A bigger run lowers his unit cost, but only if the product sells before it expires. His budget assumed strong sales, and he isn’t sure what happens if demand comes in lower.
What we do: We build base, downside, and upside forecasts using different sales volumes and the new unit cost. The downside case shows that if sales are 25% lower, part of the bigger run could expire before it sells.
The result: Kyle orders a run 50% bigger instead of doubling it. He still gets a better unit price, but with far less risk of inventory expiring on the shelf.
What Does a Full-Year Forecast Update Look Like for a Supplement Brand?
Show the original budget, the updated forecast, and a simple bridge that explains the difference. Here’s an illustrative example. The original budget:
| Line | Original Budget |
| Revenue | $2,400,000 |
| COGS (35%) | $840,000 |
| Gross profit | $1,560,000 |
| Operating expenses | $1,260,000 |
| Operating profit | $300,000 |
After four months, sales are below plan, unit costs are higher, ads are slightly over budget, and a hire started early. The updated forecast shows $205,000 in operating profit. Here’s where the $95,000 went:
| Bridge Item | Effect on Operating Profit |
|---|---|
| Original budgeted operating profit | $300,000 |
| Lower sales ($120,000 less revenue at a 65% gross margin) | −$78,000 |
| Higher unit costs (COGS rises from 35% to 36% of the new $2,280,000 revenue) | −$22,800 |
| Lower selling costs from fewer orders | +$20,000 |
| Extra advertising | −$8,200 |
| Earlier hire | −$6,000 |
| Updated forecast operating profit | $205,000 |
The bridge is what makes the forecast useful. Instead of “profit is down $95,000,” you can see that most of it came from lower sales, and decide whether to fix sales, cut costs, or both.
Final Thought: Does Your Supplement Brand’s Forecast Tell You What to Do Next?
A budget sets the target, and a forecast tells you where you’re really heading. Build both from real drivers like subscribers, unit costs, and production dates. Compare them every month, and explain each gap. When the forecast moves, you’ll know why, and you’ll have time to act.
Once your numbers point the way, our free roadmap for planning your next stage helps you turn the forecast into clear growth decisions.